Backtesting—running a strategy against historical data to see how it would have performed—is the step that separates an idea from a tradable plan. Testing only in one kind of market hides how a strategy behaves when trends reverse or prices stall in a range. The work is to replay bullish, bearish, and rangebound periods and judge whether the results hold up.
Why Backtesting Matters
Backtesting is an indispensable component of trading strategy development because it allows traders to gauge a strategy's performance over time, identify its strengths and weaknesses, and refine it before putting it into practice.
By analyzing historical data, traders can gain valuable insights into how their strategy would have performed in various market conditions, including upward trends, downward trends, and consolidations.
Testing Strategies Under Different Market Regimes
To get the most out of backtesting, it's essential to test strategies under different market regimes that reflect the environments they will encounter in real-time. Here are some guidelines for testing bullish, bearish, and rangebound strategies:
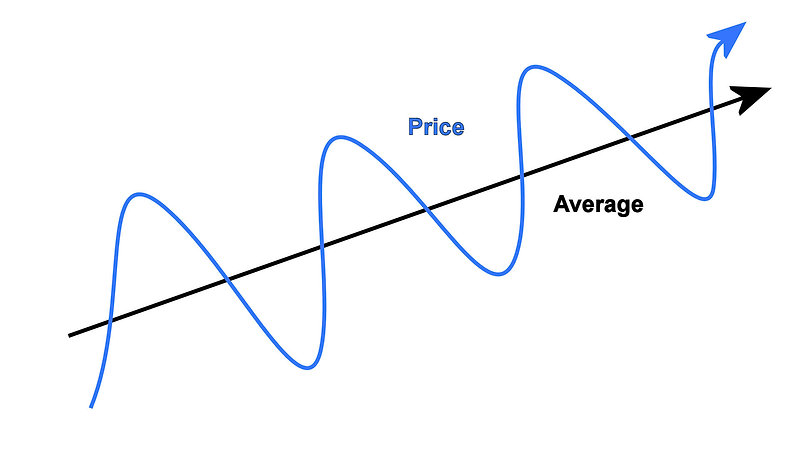
Bullish Strategies: Test bullish strategies during upwardly trending market environments of the past. This will help you evaluate how well your strategy performs when prices are rising steadily or experiencing sudden spikes. Look for strategies that consistently generate profits during bull markets, as these will be more likely to perform well in similar conditions in the future.
Bearish Strategies: Conversely, test bearish strategies during downwardly trending market environments. This will help you assess how your strategy performs when prices are declining or experiencing sharp corrections. Identify strategies that can effectively trade bear markets and generate profits during periods of market downturns.
Rangebound Strategies: When testing rangebound strategies, focus on consolidating markets where prices have been trading within a narrow band. Rangebound strategies should be able to identify and capitalize on trading opportunities within these ranges, often through the use of mean reversion techniques or other forms of technical analysis.
The Importance of Realistic Backtesting
When backtesting, it's important to use realistic market conditions and avoid cherry-picking data that might distort your results. This includes:
Using historical data that reflects the actual market conditions at the time
Avoiding over-optimization by using walk-forward optimization or other techniques that can lead to unrealistic performance
Testing multiple scenarios and stress-testing strategies under extreme market conditions
Benefits of Backtesting
By backtesting your trading strategy under different market regimes, you can:
Refine Your Strategy: Identify areas for improvement and refine your strategy to better suit the market conditions it will encounter.
Gain Confidence: Test your strategy in various scenarios, giving you confidence that it can perform well in real-world markets.
Improve Risk Management: Develop strategies that are designed to work through different market environments, reducing risk and increasing potential returns.
What matters
Backtesting is a vital component of trading strategy development, allowing traders to evaluate their approaches under realistic market conditions.
By testing bullish, bearish, and rangebound strategies in historical data, traders can refine their strategies, gain confidence, and improve risk management. In current markets, backtesting is an essential step in developing effective trading strategies that can withstand the challenges of real-world markets.
Additional Tips for Effective Backtesting
Use a reliable data source: Ensure your historical data reflects the actual market conditions at the time.
Test multiple scenarios: Stress-test your strategy under extreme market conditions to gauge its resilience.
Monitor and adjust: Continuously monitor your backtesting results and refine your strategy as needed.
Diversify your testing: Test your strategy across different markets, instruments, and time frames to improve its overall performance.
A backtest is only as honest as the data behind it. If that history is cherry-picked or the rules are over-optimized to fit it, the results flatter a strategy that will not survive live markets. Before committing capital, check the walk-forward results and stress-test the rules against an extreme period.